The National Assembly has adopted Resolution 43/2026/QH16, introducing tax relief for enterprises and organisations with annual revenue not exceeding VND 10 billion. Here are the key points for businesses.
Eligible entities
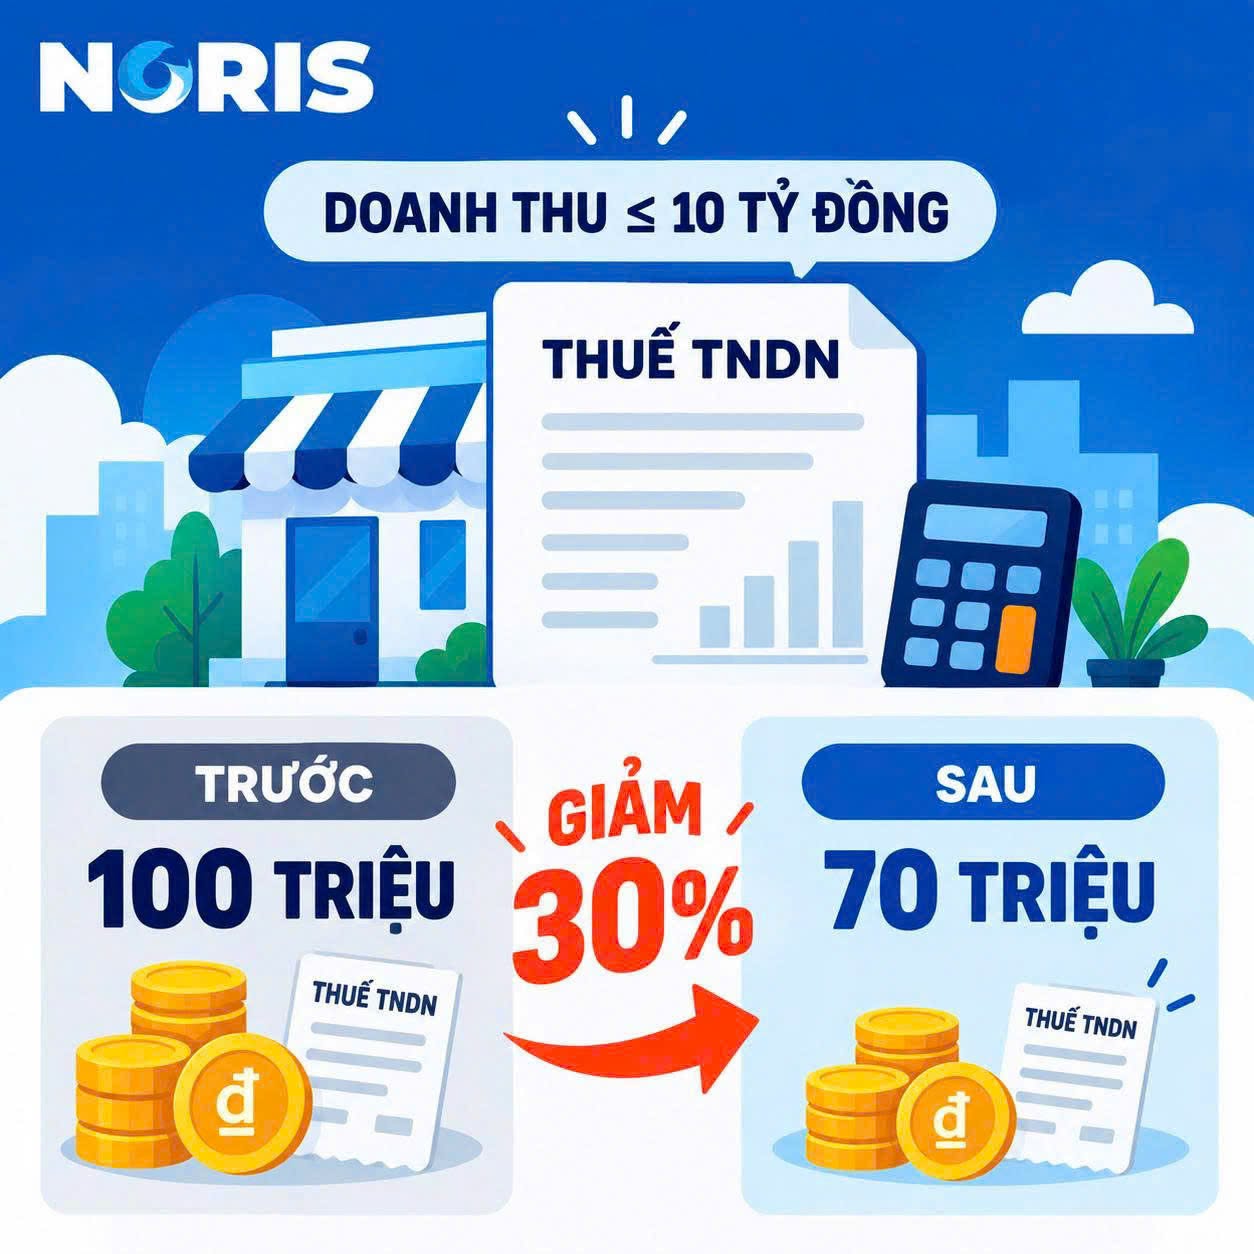
The relief is intended for enterprises and organisations established under Vietnamese law with annual revenue not exceeding VND 10 billion in 2026 or 2027.
The Resolution takes effect on 24 August 2026 and applies to the 2026 and 2027 tax periods.
How is the 30% reduction calculated?
The reduction is 30% of the corporate income tax payable. It is not a 30% reduction in revenue, nor does it automatically reduce the tax rate from 20% to 14%.
For example, a business calculates its corporate income tax payable for 2026 at VND 100 million. If its revenue for that year does not exceed VND 10 billion and it satisfies all applicable conditions, the reduction is VND 30 million, leaving VND 70 million payable.
Important considerations
- Where a business benefits from other tax incentives, the 30% reduction is calculated on the corporate income tax payable after those incentives have been deducted.
- In cases of company division or separation, the Resolution excludes certain enterprises formed after 24 August 2026 where the combined annual revenue of the resulting enterprises exceeds VND 10 billion.
How to apply the relief
The Government is finalising a decree setting out how the relief will apply. Businesses should monitor official guidance on filing procedures, provisional tax payments and claiming the reduction.
This article provides general legal information. Businesses should check the specific eligibility requirements and implementing guidance applicable when filing their tax returns.